Capituro
Apartment and Multifamily DSCR

Apartment DSCR Loans.

A long-term loan on an apartment building that's already rented, based on what the building earns.

Program Snapshot
$500K
Minimum loan
$30M
Maximum loan
5 to 300+
Units
75%
Maximum LTV
Purchase, rate-and-term, and cash-out refinance
30 year fixed or 5, 7, and 10 year fixed options
No prepayment penalty on select loans
Program Overview

DSCR-style financing for stabilized apartment buildings.

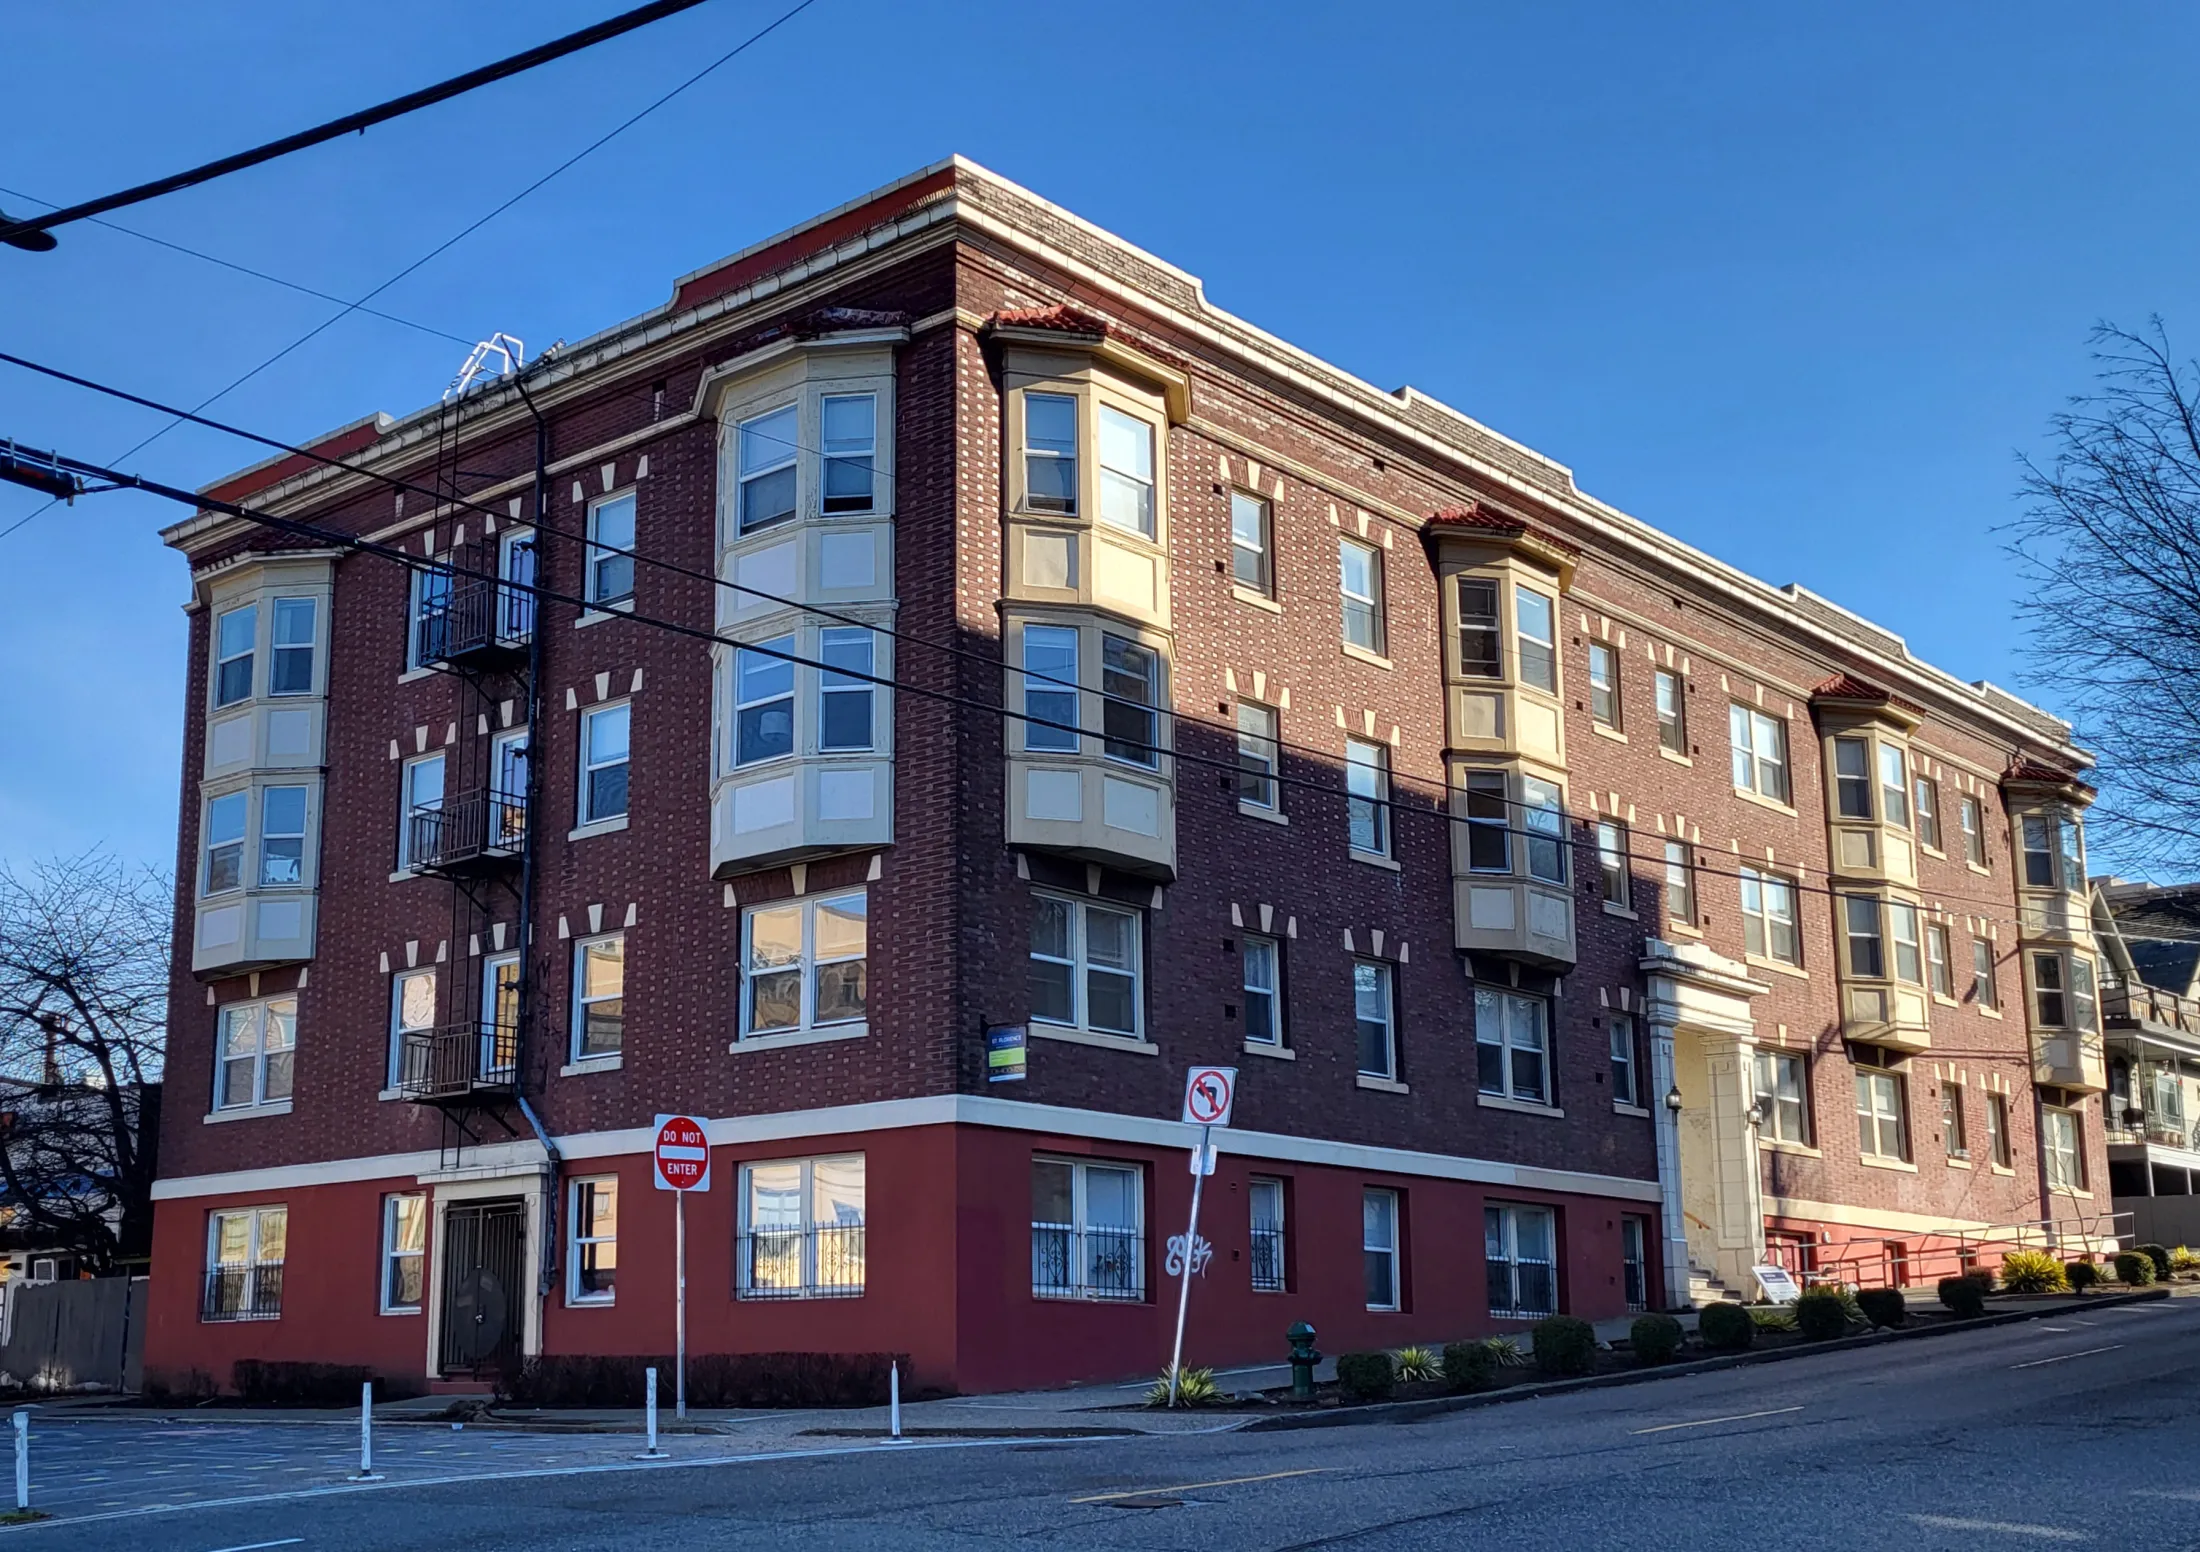
This program is for apartment buildings that are already leased up and cash flowing. DSCR-style financing means the loan is built around that building. The rent roll and the operating history carry most of the weight, and a 14 unit building and a 140 unit building get the same approach: the income comes first.

Once a building is stabilized, most owners want one of two things. Some want a 30 year fixed rate and a payment that never changes. Others want a shorter fixed period, often with no prepayment penalty, so they can sell or refinance when the timing is right. Both are available on up to a 30 year amortization.

We review loan requests across the country, including for apartment buildings in Colorado, Texas, Florida, Georgia, Tennessee, Pennsylvania, Illinois, Washington, and Montana.

Typical terms

What you can typically borrow

On 5 to 300 unit apartment and multifamily properties, loan amounts typically range from $500,000 to $30 million. Maximum LTV is typically 75% on refinances and purchases.

These are typical ranges, not a quote. Final terms depend on NOI, occupancy, property conditions, credit, and market.
Primary use
RefinanceRate and term, cash out refinance, and a bridge loan. Also available on purchases.
Loan amount
$500,000 to $30,000,000
Unit count
5 to 300+
Maximum LTV
75%Including cash out refinances on stabilized assets
Property type
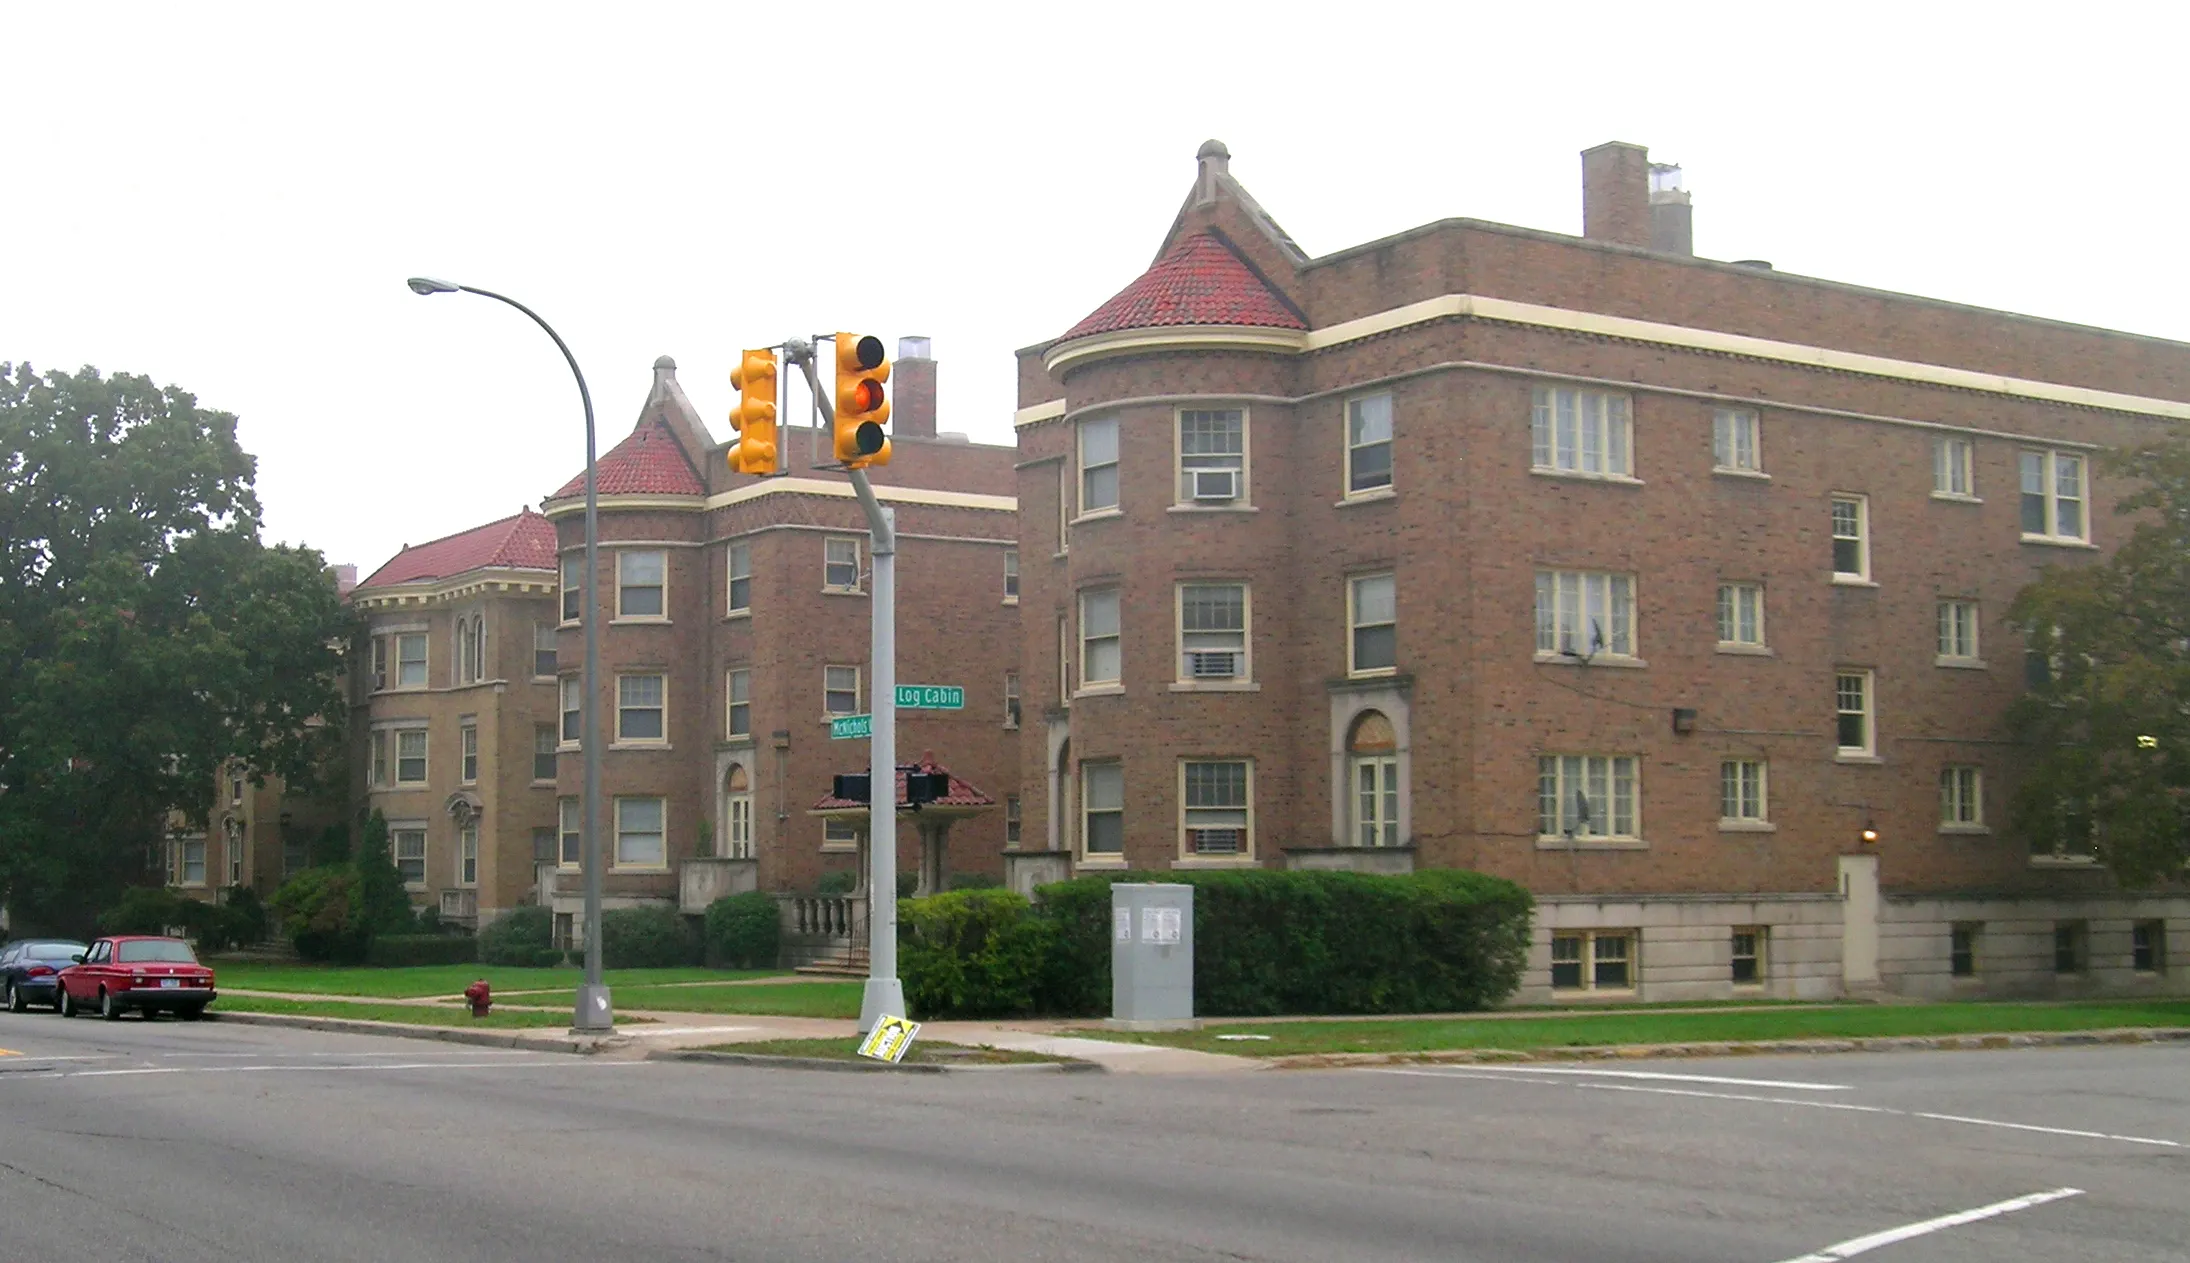
Stabilized apartment and multifamilyGarden, mid-rise, student, affordable, and mixed use
Minimum DSCR
0.90x to 1.25xDepending on loan amount and structure
Portfolios
One building or severalScattered site and multi-property loans considered
Loan term
30 year maximum5, 7, and 10 year fixed options available
Amortization
30 year maximumInterest-only periods available
Minimum FICO
660
Minimum occupancy
70%Physical occupancy at close
Prepayment
None or step down5/4/3/2/1, or none
Recourse
Full recourse typicalLimited recourse considered case by case
Available in
35 statesAL, AK, AR, CO, CT, DE, FL, GA, HI, IL, IN, IA, KS, KY, LA, ME, MD, MA, MS, MO, MT, NE, NH, NM, OH, OK, PA, SC, TN, TX, VA, WA, WV, WI, WY, DC. Very rural areas within these states may be restricted.
Buying or refinancing an apartment building?
Send the numbers, and we'll come back with a quote.
Get a Quote
Property types

Property types we like

Sound like your building?
Send the address and unit count, and we'll come back with a quote.
Get a Quote

Built for apartment owners

This loan is meant to stay with the building for as long as you own it.

1

You want to hold for the long run

A 30 year fixed rate means the payment you make in year one is the payment you make in year twenty.

2

You might sell or refinance in a few years

A shorter fixed period with no prepayment penalty keeps your exit open, whenever it comes.

3

You're fixing it up first

Bridge to buy and stabilize, then refinance into this loan once the units are leased. Both pieces can be quoted together up front.

Apartment DSCR Questions

Frequently asked

What is an apartment DSCR loan?+
A long-term loan on an apartment building based on the building's income rather than your personal income. The property's net operating income is measured against the mortgage payment, and that ratio, together with the appraised value, sets how much you can borrow.
How much can I borrow on an apartment building?+
Up to 75% of the value on a purchase or a cash-out refinance. A building with strong income relative to the payment can reach the full 75%. A building with thinner income may land a little lower.
Can I borrow more than 75% of the value?+
On select loans, yes. Our loan typically tops out at 75%. Seller financing or other subordinate debt behind it can bring total financing to as much as 90% of the value, as long as you keep at least 10% of your own equity in the building. That structure is most useful on purchases, and on cash-out refinances where the first mortgage alone leaves you short of what you need.
How is an apartment refinance underwritten?+
Underwriting is NOI based. We review trailing twelve-month operating statements, current rent roll, physical occupancy, capital improvements, and sponsor strength. DSCR is calculated from net operating income against the proposed loan payment. Minimum occupancy is typically 70% at close.
Can I cash out a recently purchased apartment building?+
Yes on select deals. Property seasoning can go as low as 1 day on DSCR cash out. For 5+ unit and commercial property, no-seasoning cash out up to 75% LTV generally requires distressed acquisition, improved occupancy since purchase, or completed rehab that explains why value exceeds the recent purchase price.
Is this loan recourse or non-recourse?+
Most apartment loans on this program are full recourse with a personal guaranty. Limited recourse is considered case by case, usually on larger loans with lower leverage.
Is there a prepayment penalty?+
It depends on the structure. A 30 year fixed sometimes carries a step-down or declining prepayment penalty. Some 5 year fixed loans carry no prepayment penalty at all. If you think you'll sell or refinance early, let us know.
Can I get interest-only payments?+
Yes. Interest-only periods are available on this loan. Full-term interest-only is meant for lease-up, while the building is still filling up. A building that has been under 80% occupied for months is a different situation. See Interest-Only Apartment Loans.
What are the downsides of an apartment DSCR loan?+
Usually a higher rate than a bank, a prepayment penalty on most loans, and an underwriting NOI that's lower than the NOI on your T-12. We walk through each one, and when they're worth it, in What is the downside of an apartment DSCR loan.
Where does Capituro offer multifamily DSCR and apartment cash-out?+
In 35 states, including Florida, Texas, Georgia, Tennessee, Colorado, Pennsylvania, Illinois, Washington, Montana, Ohio, Virginia, and more. Apartment deals are reviewed on NOI, occupancy, and the plan for the building. Send the address for a first read.
Can Capituro cash out refinance an apartment building in my state?+
Yes on eligible stabilized multifamily in the 35 states we close in, including Florida, Texas, Georgia, Tennessee, Colorado, Pennsylvania, Illinois, Washington, Montana, Ohio, Virginia, and more.
Get Started

Own apartments? Let's look at the loan.

Purchase, refinance, or cash out. Send the numbers, and we'll come back with a quote.

Step 1 of 5

What are you looking to do?

Other programs