
Wendy's, Bentonville AR
NNN loan calculator in Excel
A free spreadsheet for sizing a loan on a single-tenant net lease building. Put in the price, the rent, when the lease ends, and who's on the guaranty. It shows the loan, how it changes as the lease gets shorter, and what a prepayment penalty would cost if you sold early.
17 KB · 5 tabs · No sign-up · Excel, Google Sheets, or Numbers ·
Take years off the lease and watch the loan.
This is the example from the workbook: a made-up corporate drive-thru in Columbus, bought for $3.4 million with $187,000 of rent. Empty, the building would be worth about $1.41 million. Lenders want the loan paid down below that by the time the lease runs out.
- Years left on the lease
- 15
- Loan
- $1,826,000
- 53.7% of the price
- What sets it
- Rent
- Owed when the lease ends
- $1,297,352
- Worth $1,414,760 empty
Drag the slider. With 15 years left, the loan is paid down below the empty-building value before the lease ends, so the rent sets it.
It sizes the loan three ways and uses the smallest.
Most calculators stop at value and DSCR. On a single-tenant building, the lease term check is the one people forget, and it matters most at refinance.
75% of the $3.4M price.
Paid down to $1.41M, the empty-building value, by the time the 15 year lease ends.
$177,402 of NOI covers the payment 1.35 times at 6%.
The rent sets this one, at 53.7% of the price. That's common on net lease right now because cap rates are close to loan rates. The lease term check alone would allow $1,991,000. Drop below about 12 years left and the lease term takes over, which is what the chart above is showing.
What it costs to sell early.
Most bank and life company net lease loans carry a step-down or yield maintenance. Yield maintenance charges the lender's spread over Treasuries for every year left, so it's worst early on.
- No prepayment penalty
- $0
- Step-down, 5-4-3-2-1
- $52,635
- Yield maintenance
- $213,929
On the $1,826,000 example loan. Tap a year to compare.
What's in the file
Five tabs. You only type on Inputs, and the guarantor is a drop-down. The rest is regular formulas with no macros, so it works in Google Sheets and Numbers too.
- 1Property and lease
Price, square feet, rent, and the year the firm term ends. Leave out renewal options; lenders don't count them until they're exercised.
- 2Guarantor
Corporate investment grade, corporate, a franchisee with 20+ locations, or a smaller franchisee. Each has its own vacancy allowance.
- 3Rate and re-leasing
Update the 5 year Treasury (the one in the file is a placeholder), then what a new tenant would pay, months empty, and the cost to re-lease.
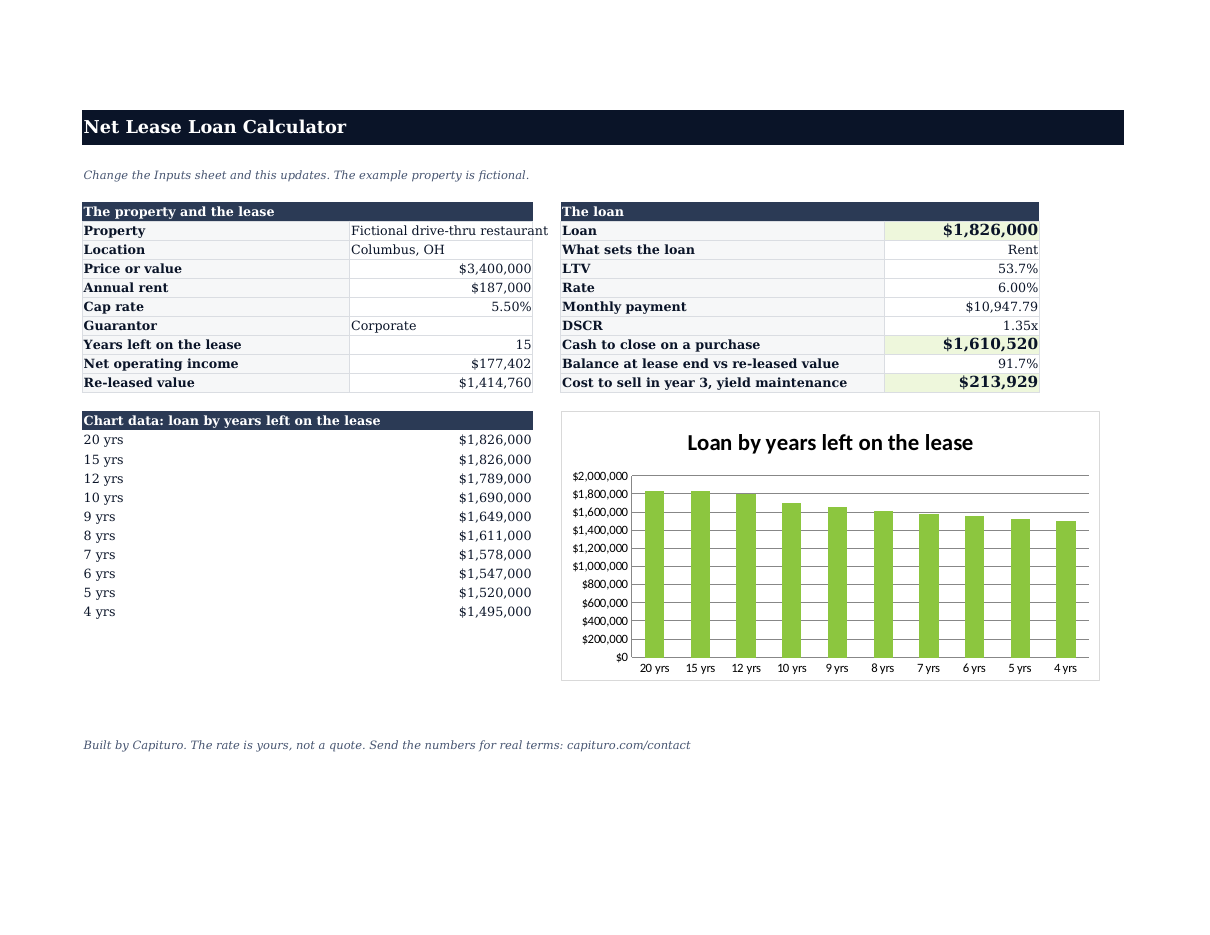
Summary: the loan and what's limiting it, the payment, DSCR, cash to close, the balance when the lease ends, and the year 3 yield maintenance cost. Open full size
If the loan comes out lower than you want
The Loan tab tells you which of the three set it. The fix depends on which one.
The rent set it
The building could carry more, but the rent can't cover a bigger payment at this rate. Higher rent, a lower rate, or a rent increase that has already kicked in will help. A higher appraisal or a longer lease won't.
The lease term set it
You'd still owe more when the lease ends than the building is worth empty. A signed extension is the main fix, and borrowing less works too. Renewal options don't count until they're exercised. Worth checking before you buy: 9 years left today is 4 left when a 5 year loan matures.
Check the market rent, months empty, and re-leasing cost. Low rent or high costs make the empty value tiny.
At low cap rates the rent usually limits it. Check the Treasury and spread.
The sale year is past the yield maintenance period, or the Treasury at sale is above the note rate.
Where this leads next
NNN and Net Lease Loans
No prepayment penalty, 30 year amortization, $1M to $30M.
OpenRestaurant NNN Loans
Drive-thru and fast casual buildings leased to national brands.
OpenMedical NNN Loans
Dialysis, urgent care, and medical buildings on a net lease.
OpenHow a net lease property gets financed
What lenders look at on a single-tenant building.
OpenQuestions
It covers single-tenant NNN and NN leases: restaurants, medical, essential retail, auto service, childcare. It doesn't model rent bumps, renewal options, ground leases, multi-tenant property, or defeasance, and it isn't a rate quote or an approval.
How much can I borrow on a net lease property?
Up to 75% of value, as long as the rent covers the payment at least 1.35 times on a 30 year amortization. With rates where they are, the 1.35x usually limits the loan before the 75% does.
How does the time left on the lease affect the loan?
With a long lease, the loan gets paid down well before the lease ends, so it doesn't matter much. With a short one, the lender wants the balance at the end of the lease to be less than what the building would be worth without the tenant. If it isn't, the loan gets smaller.
Do renewal options count toward the lease term?
No, only the firm term counts. Once a renewal option has been exercised and signed, those years count too.
Does it matter if the tenant is corporate or a franchisee?
Yes. A lease guaranteed by the brand's corporate parent is the strongest. A franchisee with 20 or more locations is also a good fit. Smaller franchisees are harder, and the workbook uses a bigger vacancy allowance for them.
What does yield maintenance cost compared to no prepayment penalty?
Yield maintenance makes you pay the lender the interest it would have earned over Treasuries for the rest of the term, so it costs the most in the first few years. In the example, selling in year 3 costs $213,929 with yield maintenance and nothing with no prepayment penalty.
Want terms on a property?
Send the price, the rent, when the lease ends, and we'll get back to you fast.