Capituro
Owner-user commercial

Owner-User Commercial Loans.

Refinance the building your business runs from onto a 25 year amortization, with up to 90% combined financing and cash out available for the business.

Program Snapshot
$1M
Minimum loan
$10M
Maximum loan
90%
Maximum combined financing
25 yr
Amortization
Industrial, manufacturing, office, warehouse, and self storage
Rate and term refinance and cash out
For established businesses
Program Overview

You own the building. Let the loan work for your business.

For a lot of business owners, the building is the biggest asset they have, and the payment on it is one of the biggest bills after payroll. A short amortization can pull more cash out of the business every month than it needs to, while years of equity sit in the building doing nothing.

Refinancing onto a 25 year amortization can lower that payment and free up equity for the business. Financing goes up to 90% combined, using a first loan and a second loan, with the rate on the second loan fixed long term.

These loans are for buildings your business occupies, and we also review purchases of a building your business will occupy. If you lease the building to other tenants, see our Commercial DSCR, Interest-Only Commercial, or NNN and Net Lease programs.

What you get
Owner-user commercialTypical bank loan
Maximum financing
Up to 90% combined
Usually 65% to 75%
Long-term fixed rate
Second loan fixed long term
Usually fixed for about 5 years
Loan size
$1M to $10M
Capped by the bank's limits
Typical terms

What you can typically borrow

These are typical ranges, not a quote. Your terms depend on the building, your business's financials, and how much equity you have.

Loan amount
$1,000,000 to $10,000,000
Loan purpose
Rate and term refinance and cash outPurchases also reviewed
Maximum financing
Up to 90% combinedA first loan and a second loan
Business history
At least 2 years in operationOn a refinance
Rate
BlendedThe second loan is fixed long term
Amortization
25 yearsFully amortizing
Property types
Industrial, manufacturing, office, warehousePlus self storage you actively operate
Occupancy
Your business occupies the buildingAt least 51% of an existing building
Income used
Your business's financialsThe business pays the rent that carries the loan
Business size
Small and mid-size businessesSize limits apply
Credit
680 and up
Guaranty
Personal guarantyFrom owners of 20% or more
Borrower
Your business or a company you ownFormed to hold the building
Available in
35 statesAL, AK, AR, CO, CT, DE, FL, GA, HI, IL, IN, IA, KS, KY, LA, ME, MD, MA, MS, MO, MT, NE, NH, NM, OH, OK, PA, SC, TN, TX, VA, WA, WV, WI, WY, DC. Very rural areas within these states may be restricted.
Note: These are typical terms. Yours depend on the building and your business's financials. These loans are subject to SBA eligibility rules and approval. Owner-user loans are for commercial buildings your business occupies, not homes.
Own the building your business runs from?
Send the address and a few numbers on your business, and we'll come back with terms.
Get a Quote
Where it fits

Businesses we like

Brick front office of a manufacturing plant with flags out front
Manufacturers

Production buildings the business has owned and grown into over the years.

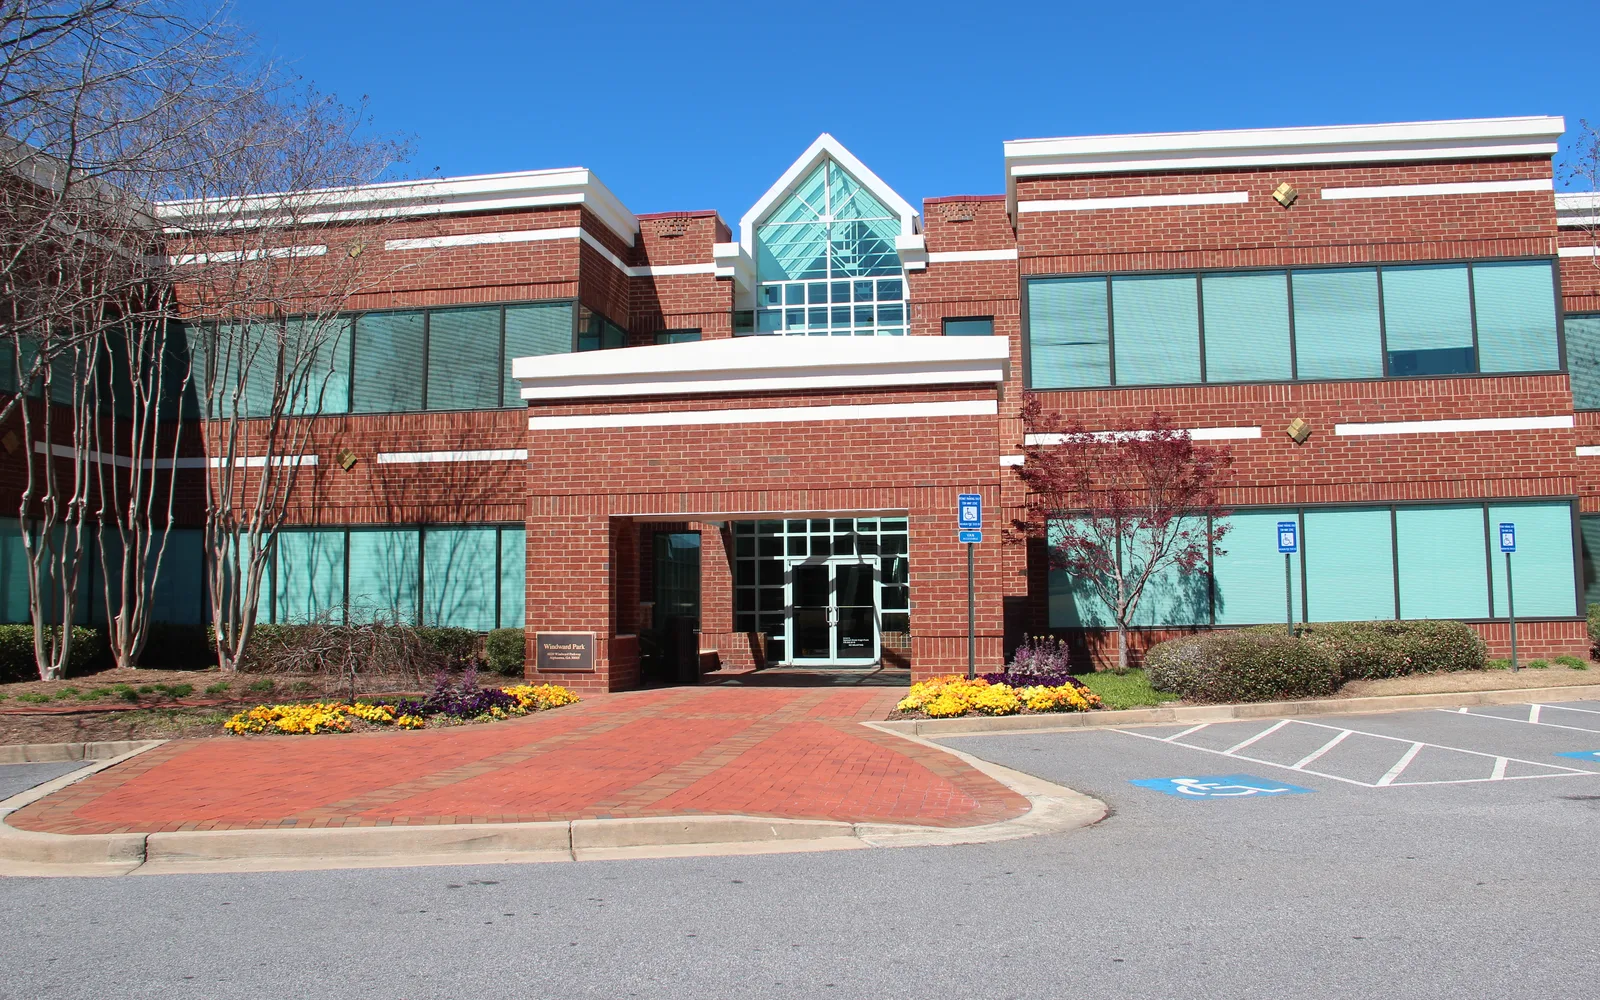
Two-story brick medical office building with a glass entry
Medical and dental practices

Office buildings a practice owns and operates from.

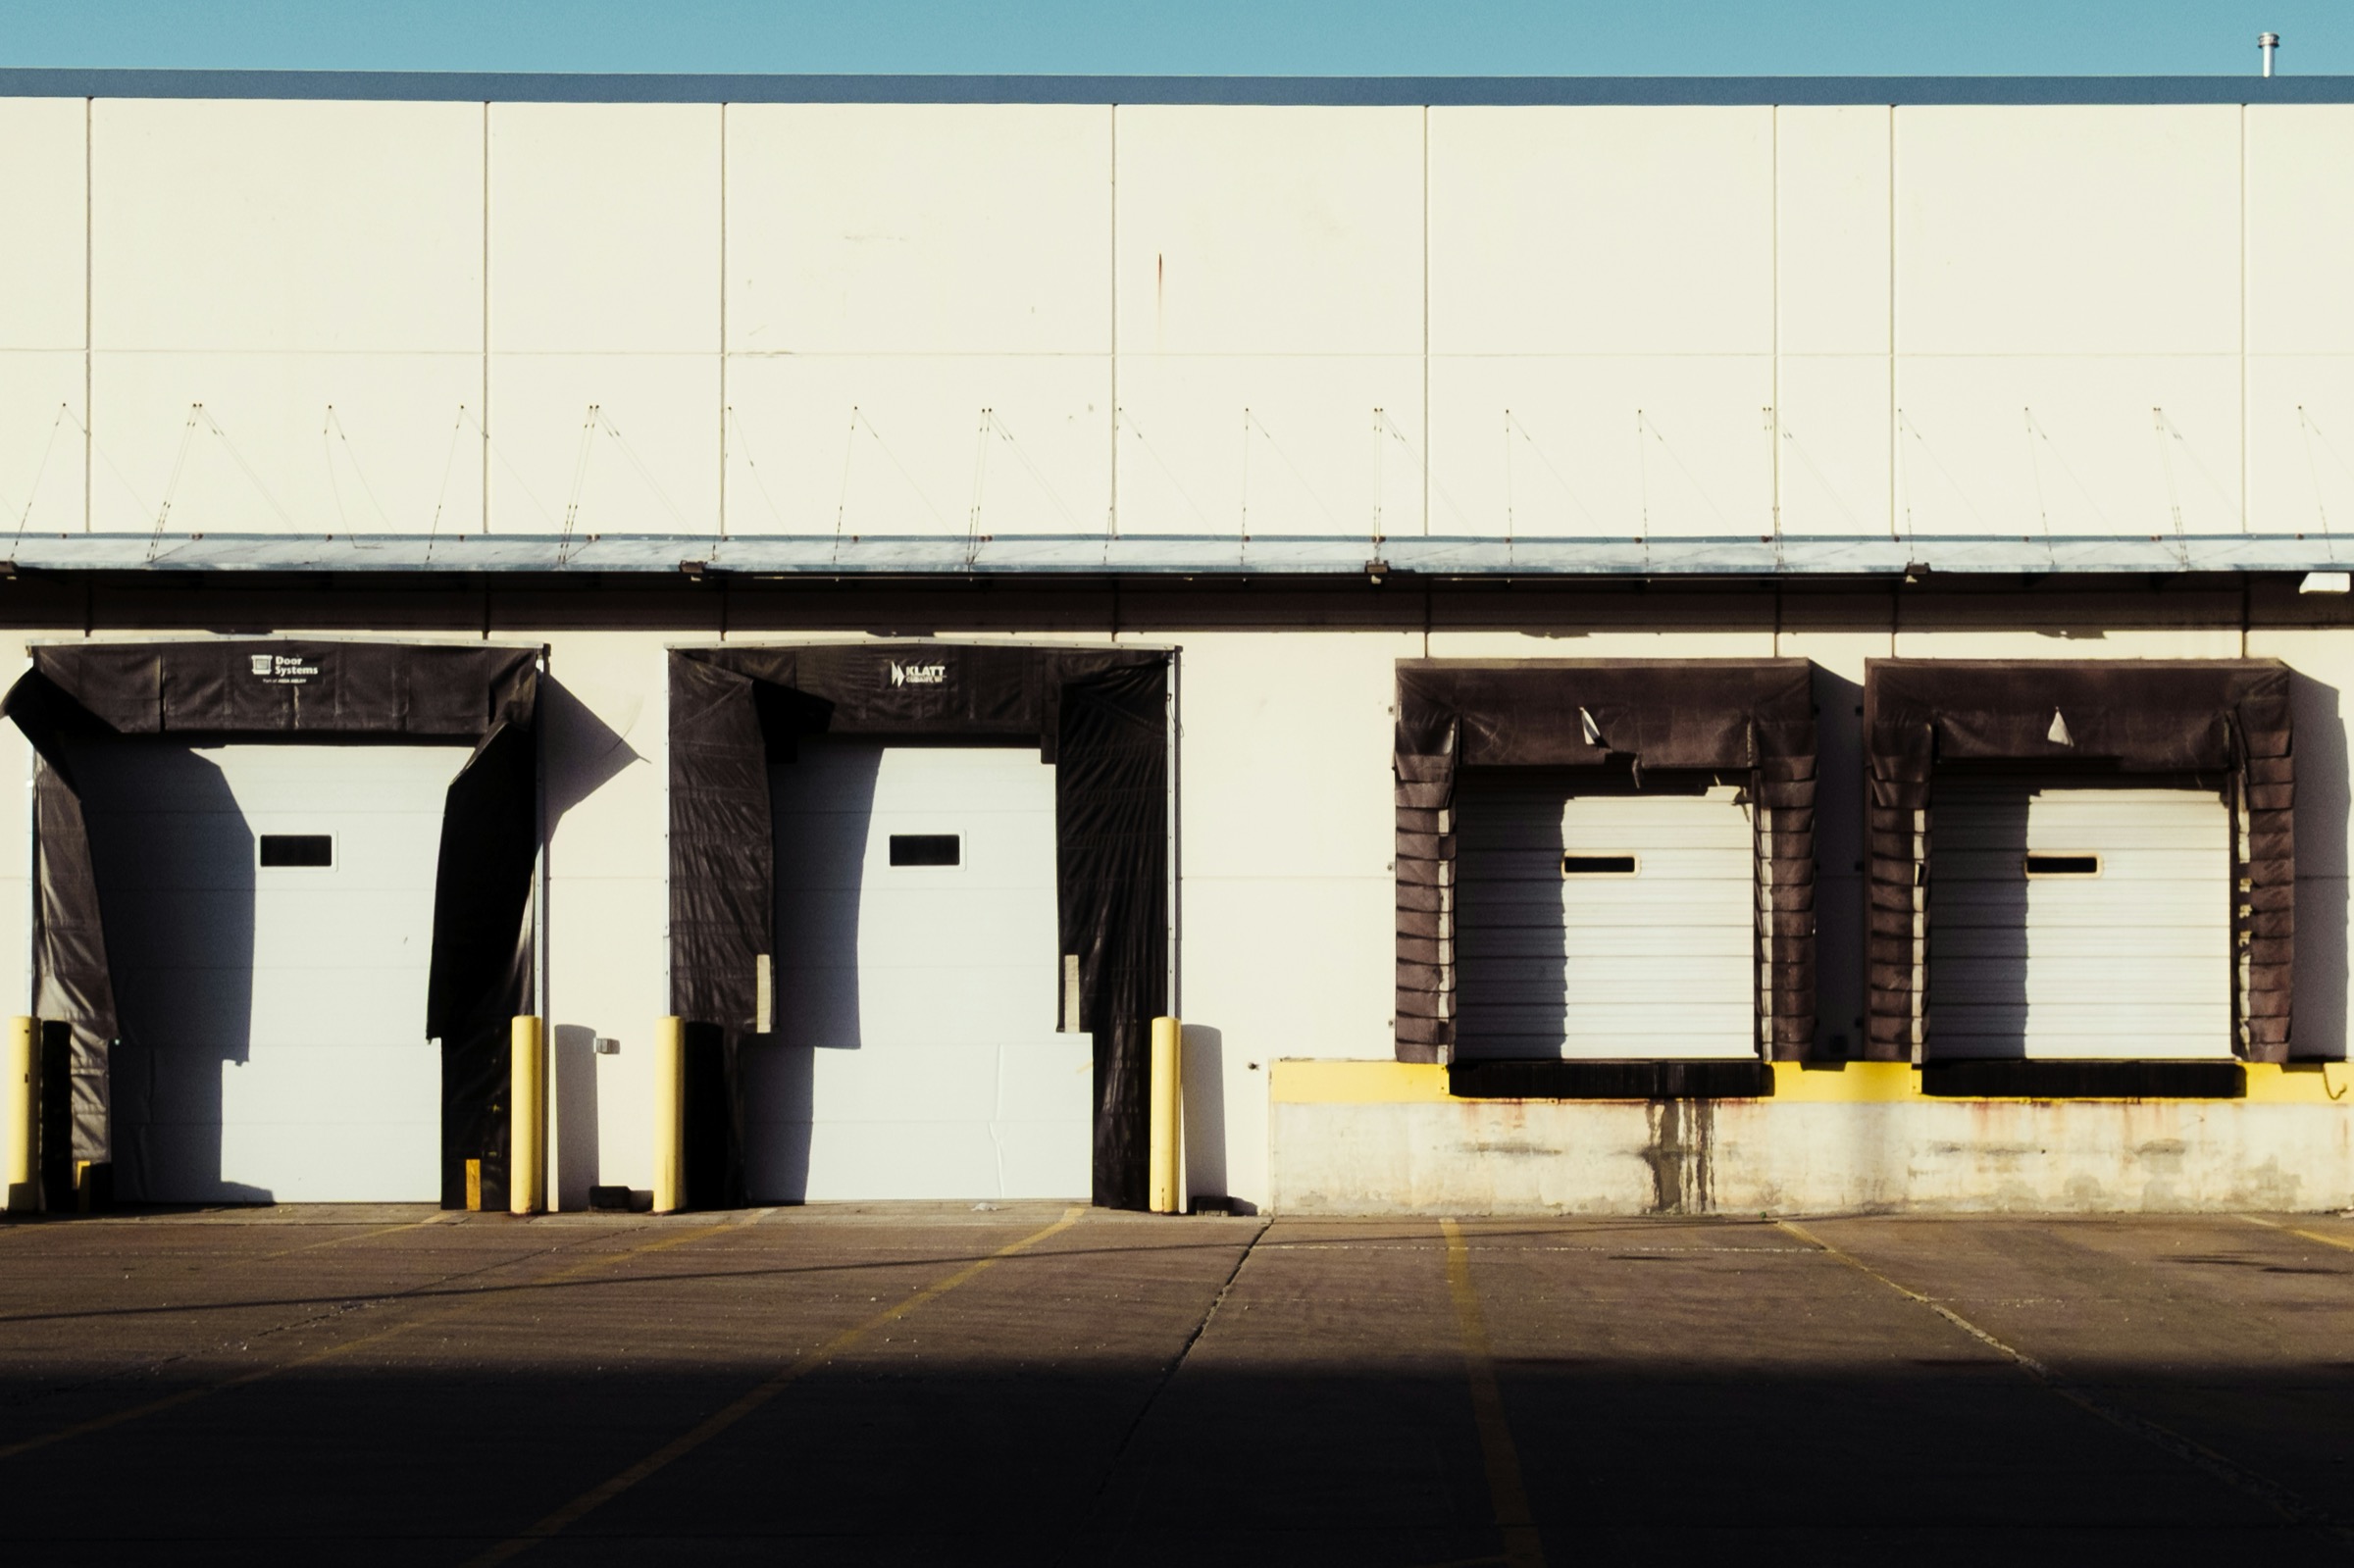
Row of loading docks on a white warehouse building
Distributors and contractors

Warehouses with loading docks, yards, and shop space.

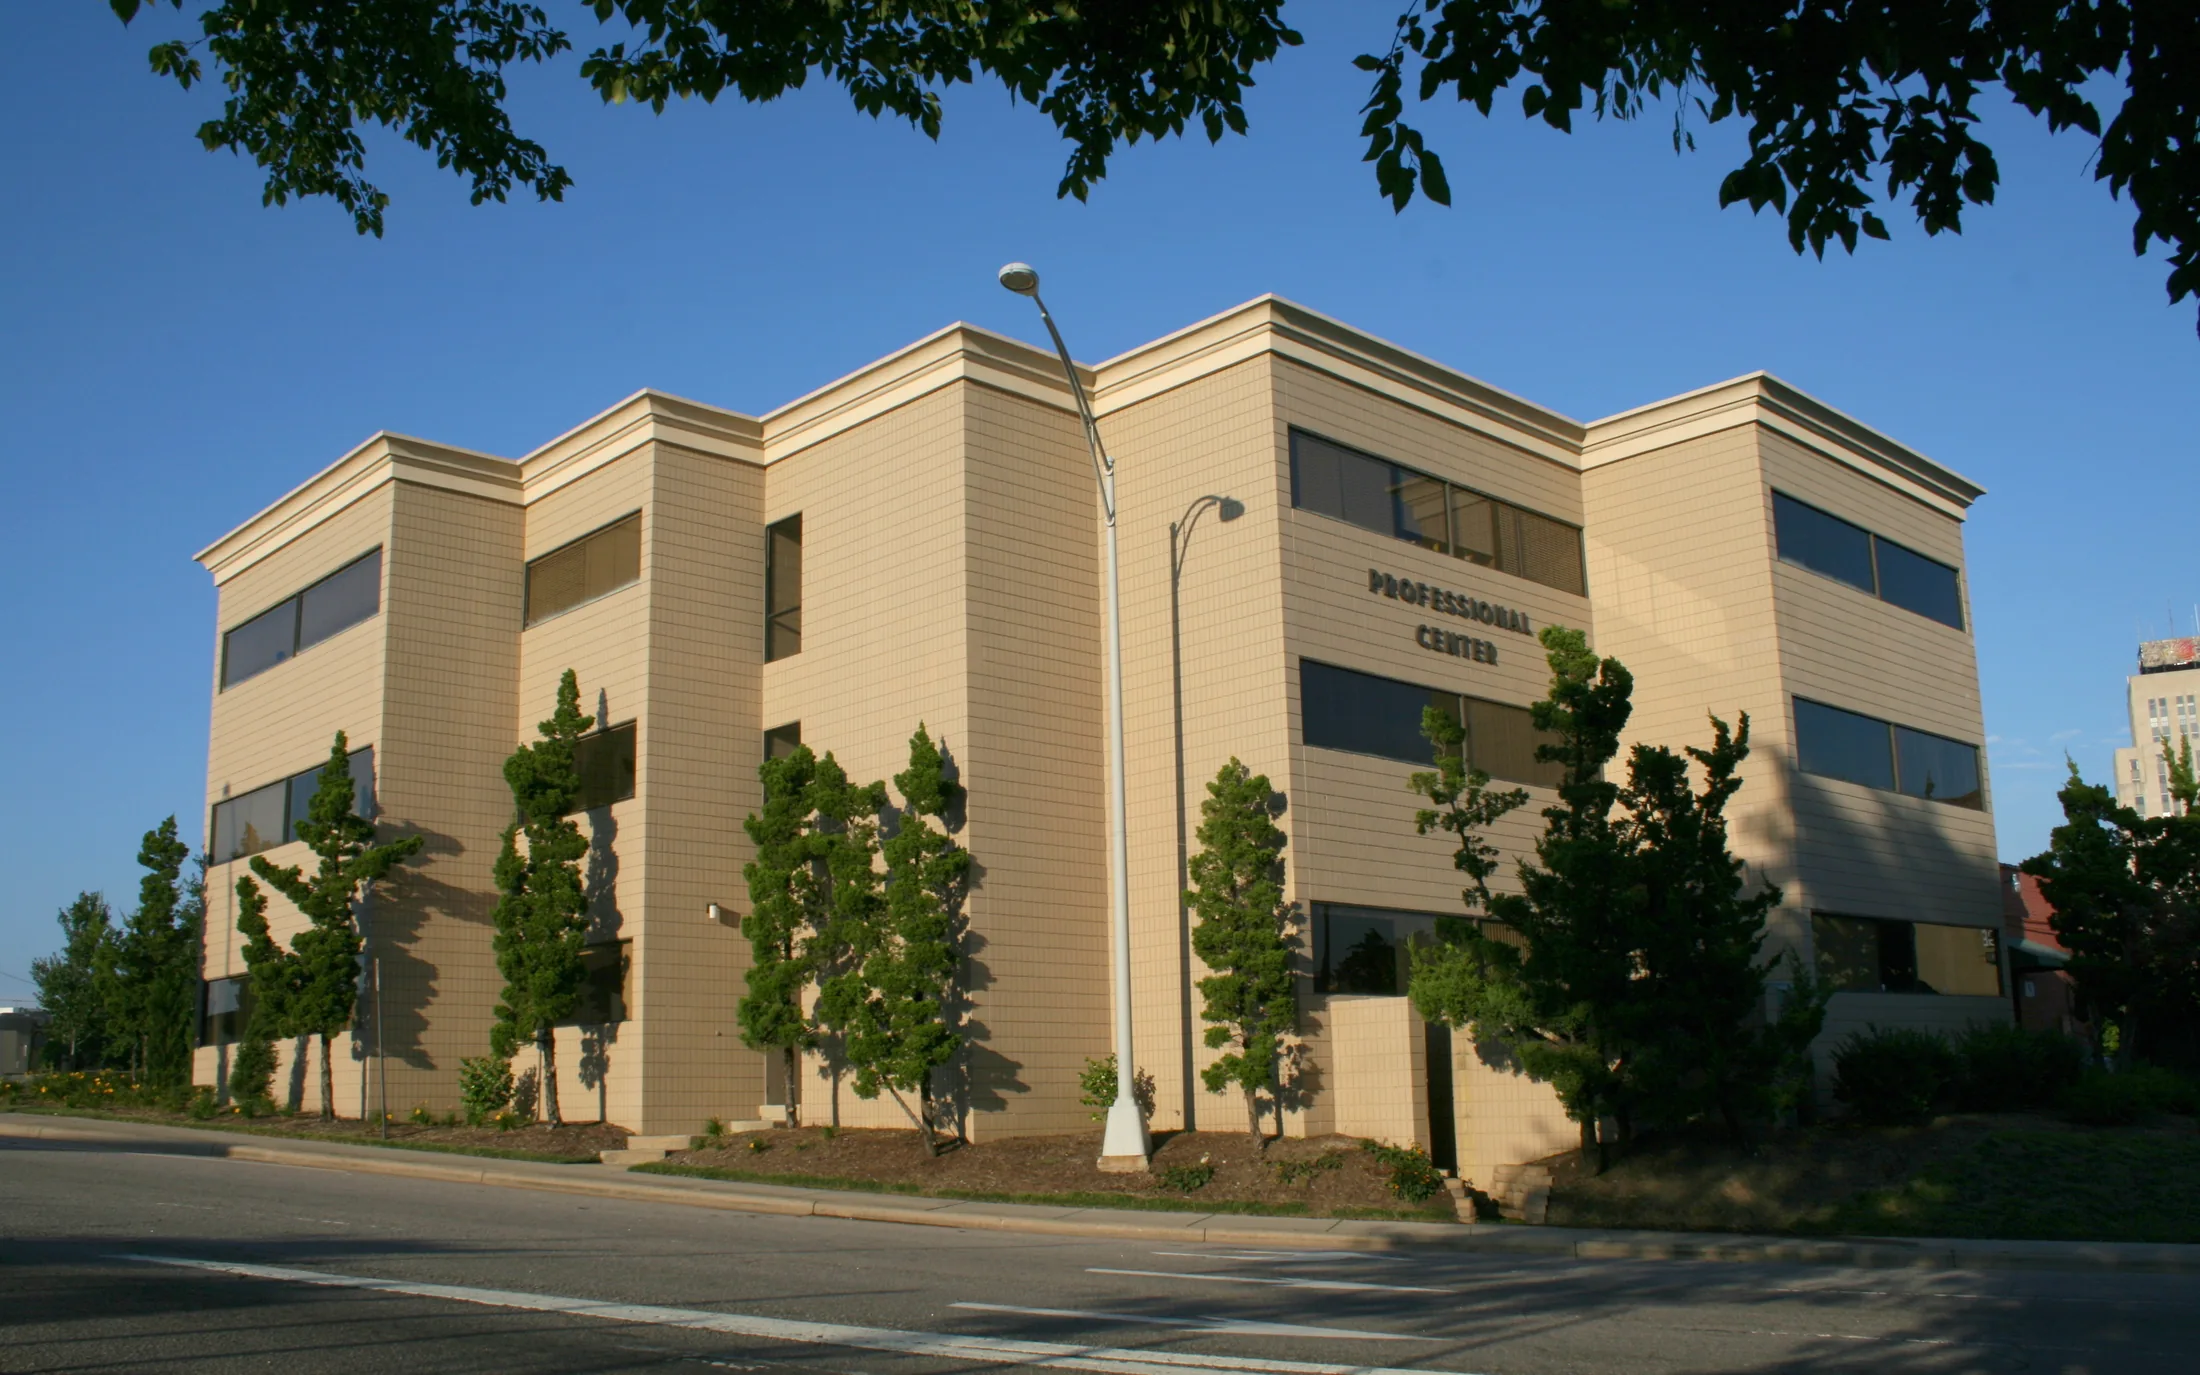
Four-story professional office building framed by trees
Professional firms

Law, accounting, and engineering firms that own their office.

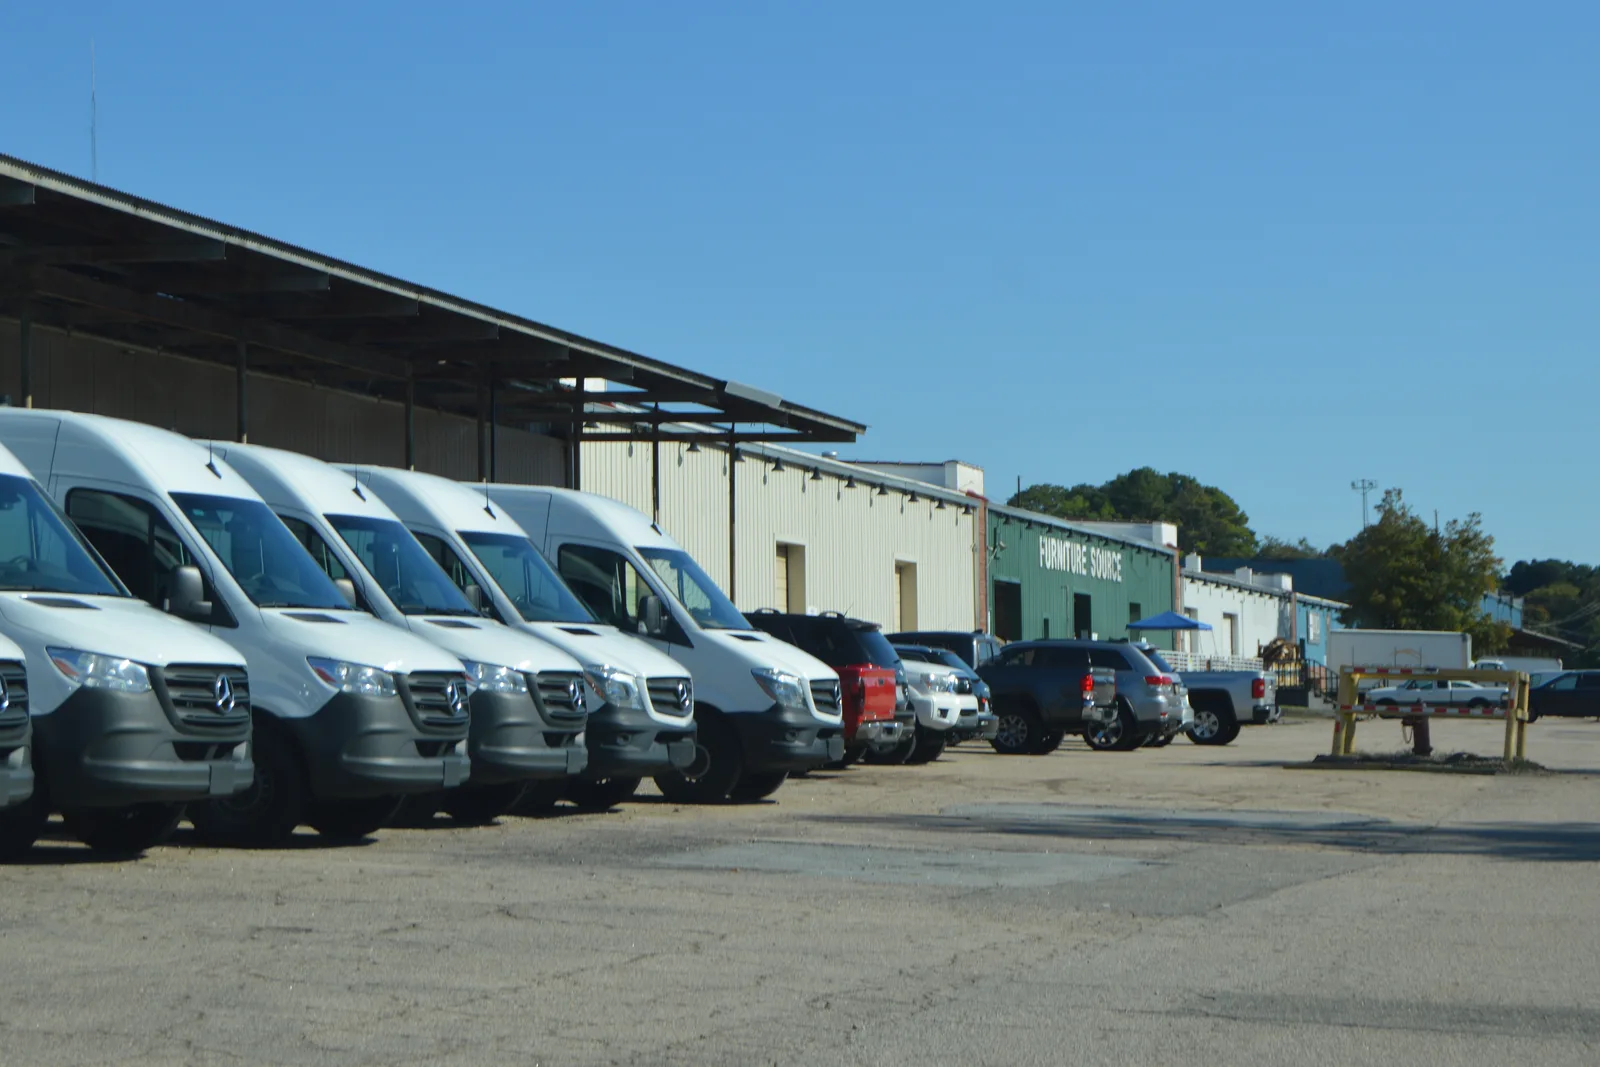
Light industrial buildings with work vans parked out front
Light industrial users

Flex buildings with shop space and an office area.

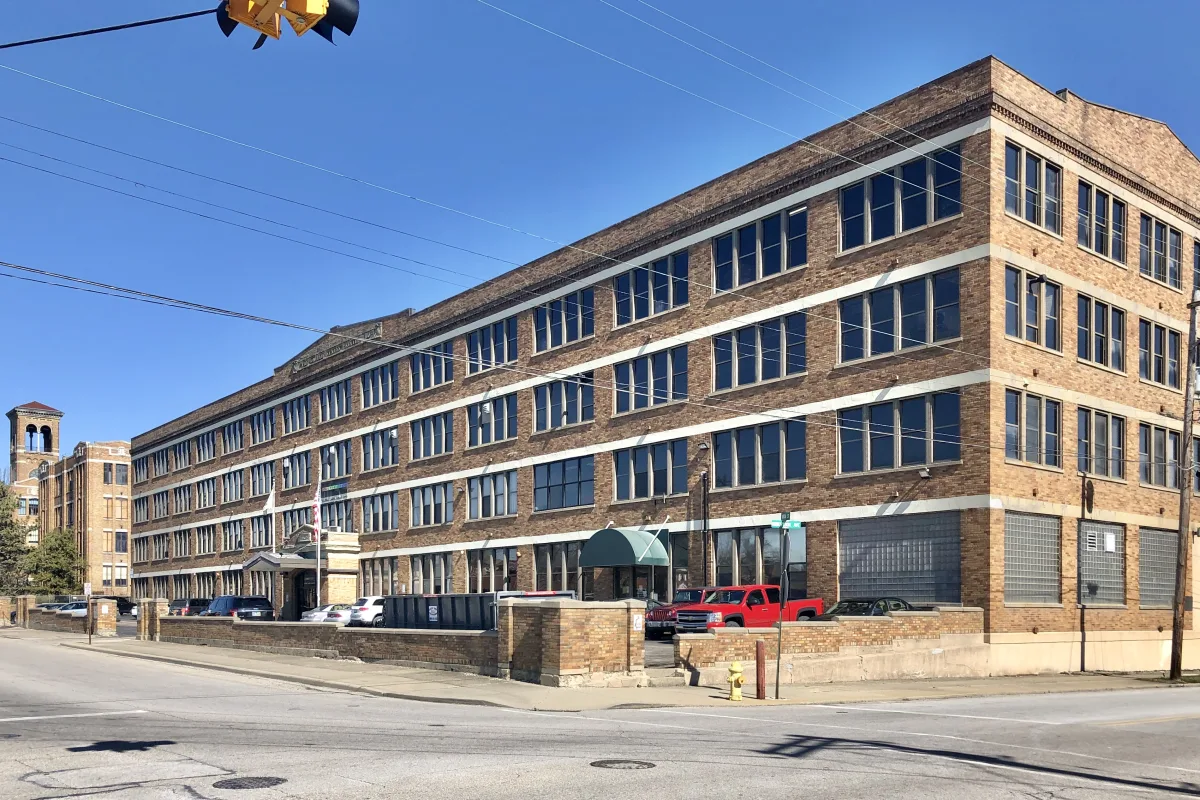
Four-story brick commercial building with rows of large windows on a city corner
Long-running family businesses

Buildings held for years, with real equity built up.

Who this is for

Built for business owners who own their building

Get a Quote
1

You want a lower monthly payment

A longer amortization leaves more of the cash flow in the business.

2

You have equity in the building

Take cash out for the expenses of running the business.

3

Your business carries other debt

Eligible business debt can sometimes be paid off in the same loan.

4

You've been operating for years

These programs are built around established businesses with a track record.

Owner-User Questions

Buying the building your business uses

What is an owner-occupied commercial real estate loan?+
A loan on a commercial building that your own business uses, like a warehouse, a manufacturing plant, or an office. Since your business is the tenant, its ability to pay carries the loan.
How much can I borrow on my business's building?+
Up to 90% combined, on loans from $1 million to $10 million.
Can I take cash out?+
Yes, as long as the cash goes to eligible expenses of running the business, like payroll, rent, inventory, or business debt. It can't go to personal expenses.
What does my existing loan need to look like?+
The loan being refinanced has to be at least 6 months old and mainly used for the building or major equipment, and the new payment on that debt has to be lower than what you pay today. Send the numbers on your current loan and we'll tell you where it stands.
How long does my business need to have been operating?+
At least 2 years for a refinance. Startups are a harder fit.
Is this an SBA loan?+
Yes. It uses the SBA 504 structure: a first loan for about 50% of the value, an SBA-backed second for about 40%, and at least 10% equity from you.
What are the rates?+
The rate is a blend of the first loan and the second loan, and the second loan is fixed long term. Send the numbers for terms on your building.
Can I own the building through a separate company?+
Yes, and it's common. Many owners hold the building in its own company and have their business lease it. The operating business is part of the loan.
What types of buildings qualify?+
Existing industrial, manufacturing, office, and warehouse buildings your business occupies, plus self storage facilities you actively operate. Homes and mixed-use buildings where you live don't qualify.
Does self storage qualify?+
Yes, when you actively run the facility yourself or with your own employees, including leasing and collections. A facility held as a passive investment or handed off to an outside manager generally doesn't fit, and our Commercial DSCR program may be the better choice.
What if my business only uses part of the building?+
Your business has to occupy at least 51% of an existing building, and you can lease the rest to other tenants. If other tenants lease most of the building, our Commercial DSCR program may fit better.
Does my business qualify?+
Most small and mid-size businesses do. The business has to be for-profit and within the program's size limits, and its owners have to be U.S. citizens or U.S. nationals. Owners of 20% or more sign a personal guaranty.
Can I use this to buy a building?+
Yes, we also review purchases of a building your business will occupy. Plan on as little as 10% down, or 15% to 20% for a business under two years old or a single-purpose building.
What if I have more equity and don't need 90%?+
Send the numbers anyway. We have other programs for owners with more equity, and we'll tell you what fits.
What credit score do I need?+
680 and up.
Where does Capituro offer owner-user commercial loans?+
In 35 states: Alabama, Alaska, Arkansas, Colorado, Connecticut, Delaware, Florida, Georgia, Hawaii, Illinois, Indiana, Iowa, Kansas, Kentucky, Louisiana, Maine, Maryland, Massachusetts, Mississippi, Missouri, Montana, Nebraska, New Hampshire, New Mexico, Ohio, Oklahoma, Pennsylvania, South Carolina, Tennessee, Texas, Virginia, Washington, West Virginia, Wisconsin, and Wyoming, plus Washington, DC. Very rural areas within these states may be restricted. Send the address and we'll confirm whether your building fits.
Get Started

Already own your building? Let's look at the loan.

Send the address and a few numbers on your business. We'll come back with terms.

Step 1 of 5

What are you looking to do?

Other programs